For private equity and enterprise leaders
AI is not the hard part. Getting value from it is.
You bought the licences. The margin did not move. We start from the numbers the business has to hit, find where AI moves them, size it, and build it with your people in the room.
72%
of operating partners name operational improvement as their top value creation lever. The financial levers are spent.
Operating Partners Technology Value Creation Survey 2026, 145 operating partners
Only 7%
of companies have AI built into how the business actually runs. The rest have licences and a pilot.
FTI Consulting, 2026 Private Equity AI Radar$3.70
returned per $1 spent on AI, and the best get $10.30. It does pay. Most are getting the low end.
IDC and Microsoft, 2,000 enterprisesWhere the experience comes from
01Why now
PE and enterprise. Different pressure, same fix.
AI is the fastest way to improve margin right now, if you use it to change how the company runs, not just to help people with their own work.
PE Portfolio
The sale price has to come from the business.
Between 2010 and 2022, leverage and multiple expansion made up about 59% of private equity returns. Neither works the way it used to, and 32,000 companies are waiting to be sold.
So the return has to come from the business itself. Bain puts the requirement at roughly 12% annual EBITDA growth, against the 5% that worked in the last cycle. (Bain, Global Private Equity Report 2026)
Enterprise
Most AI pilots never reach the P&L.
248 days
average from signed contract to production
Enterprise deployment benchmarks, 2026
88%
of pilots never graduate to production
Enterprise agent survey, 2026
5 to 8%
report measurable return on their AI spend
BCG and KPMG, 2,100+ execs
02The gap
Why are most companies struggling to get value?
The gap is not one thing. It is multi-dimensional, so fixing one part on its own does not close it.
- 01
Savings you cannot prove do not count
Nobody recorded what it cost before, so at diligence the buyer cannot verify the saving and strips it out. The improvement was real. It just did not reach the price.
- 02
Acquisitions never fully join up
Each one keeps its own systems and its own way of working. The platform never becomes one company, and the value you bought it for leaks away in the integration.
- 03
It starts in tech, not the value plan
AI arrives as an IT project. The first question is which tools, not which line of the plan moves.
- 04
Legacy systems feel like a blocker
Systems and data do not join up, so most teams assume they need years of foundation work before AI can pay. You do not.
Only 15% have mature technology
- 05
Use case hunting, in silos
Ask each function what it needs and you get a list shaped like the org chart you already have.
- 06
Processes built for a manual world
Fragmented, with manual checks and sign-offs at every step, because people make mistakes. Automate that and you automate the checking.
44% say their own approval process is too slow
- 07
Tool rollout counted as progress
Copilot and ChatGPT for everyone, some training, then wait. People get faster at their own work. The approval still waits three days. Nothing reaches the P&L.
- 08
The stack and architecture are different
Architecture for an AI-native business has almost nothing in common with the one built for personal productivity.
03What we work on
Rolling out a tool does not change how the business runs.
Buying a tool changes what your people can do. Changing how you operate changes what the business earns. That means seven areas changing together. Leave one behind and you lose value in the others.
01 of 7
Value & strategy
Start from the value creation plan or the targets the board has set. Find where AI moves a number, size it, and give it one owner.
All seven have to change together. Leave one behind and you lose value in the others.
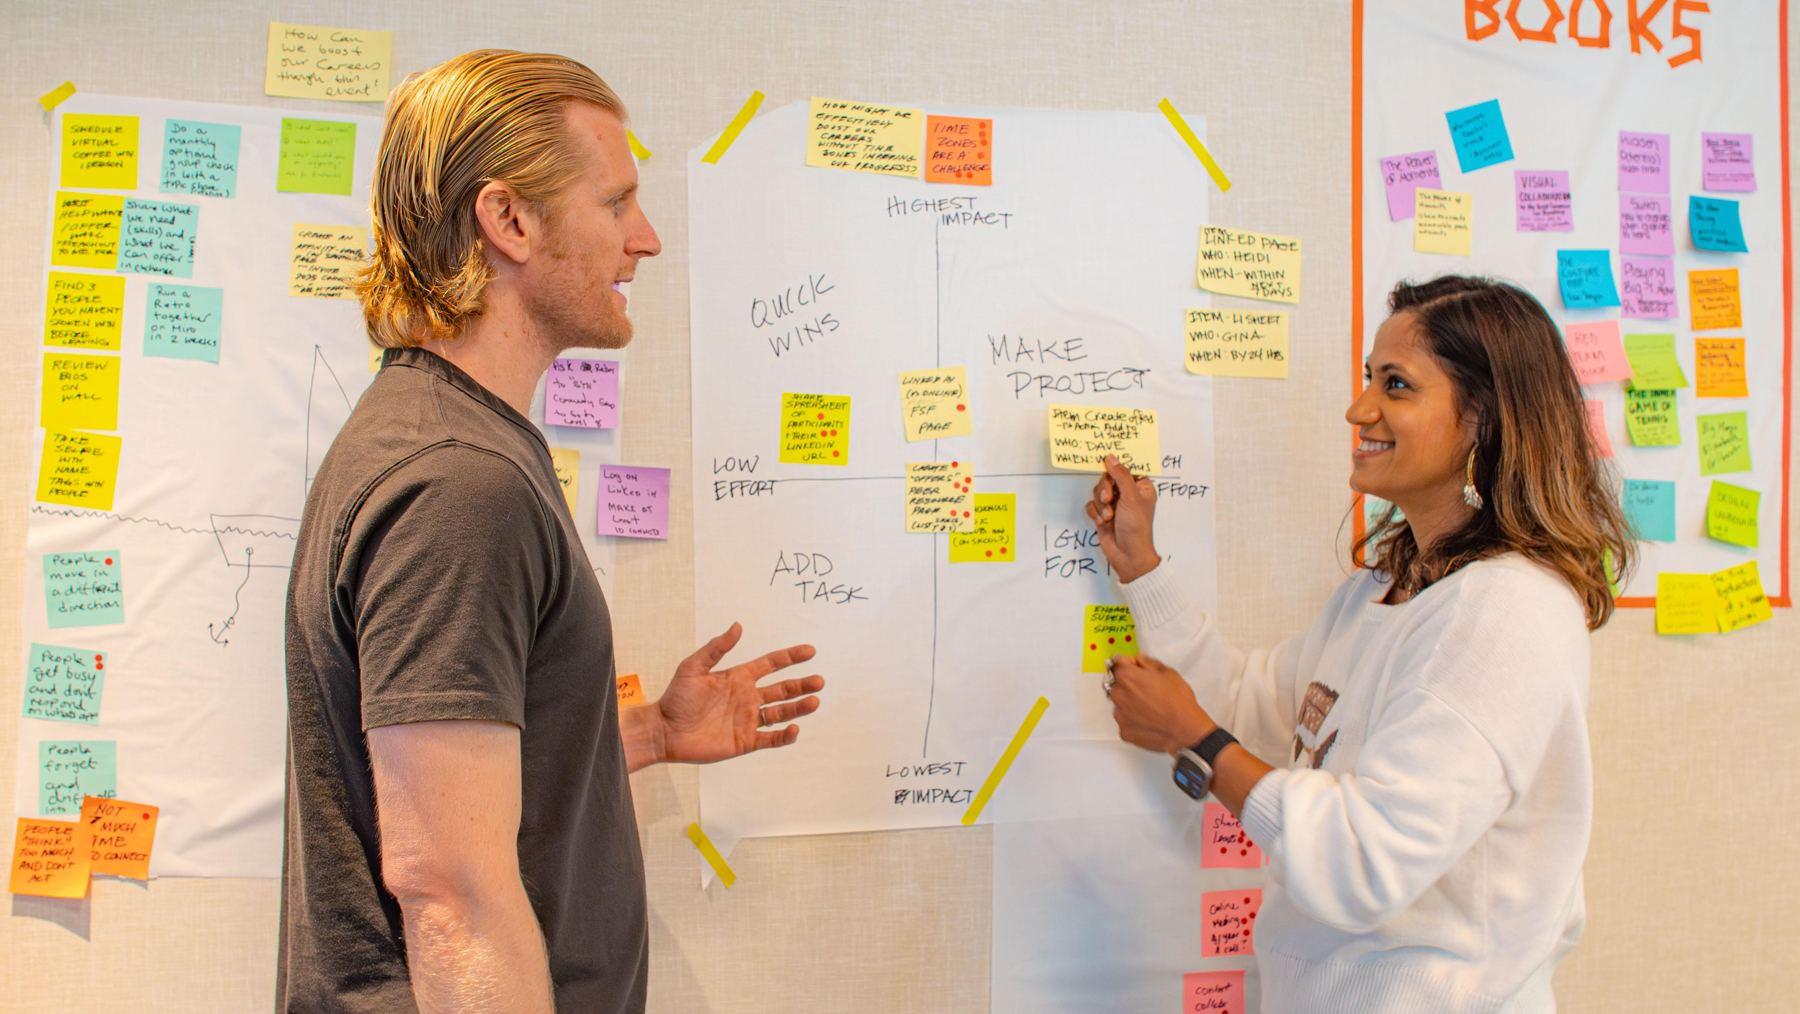
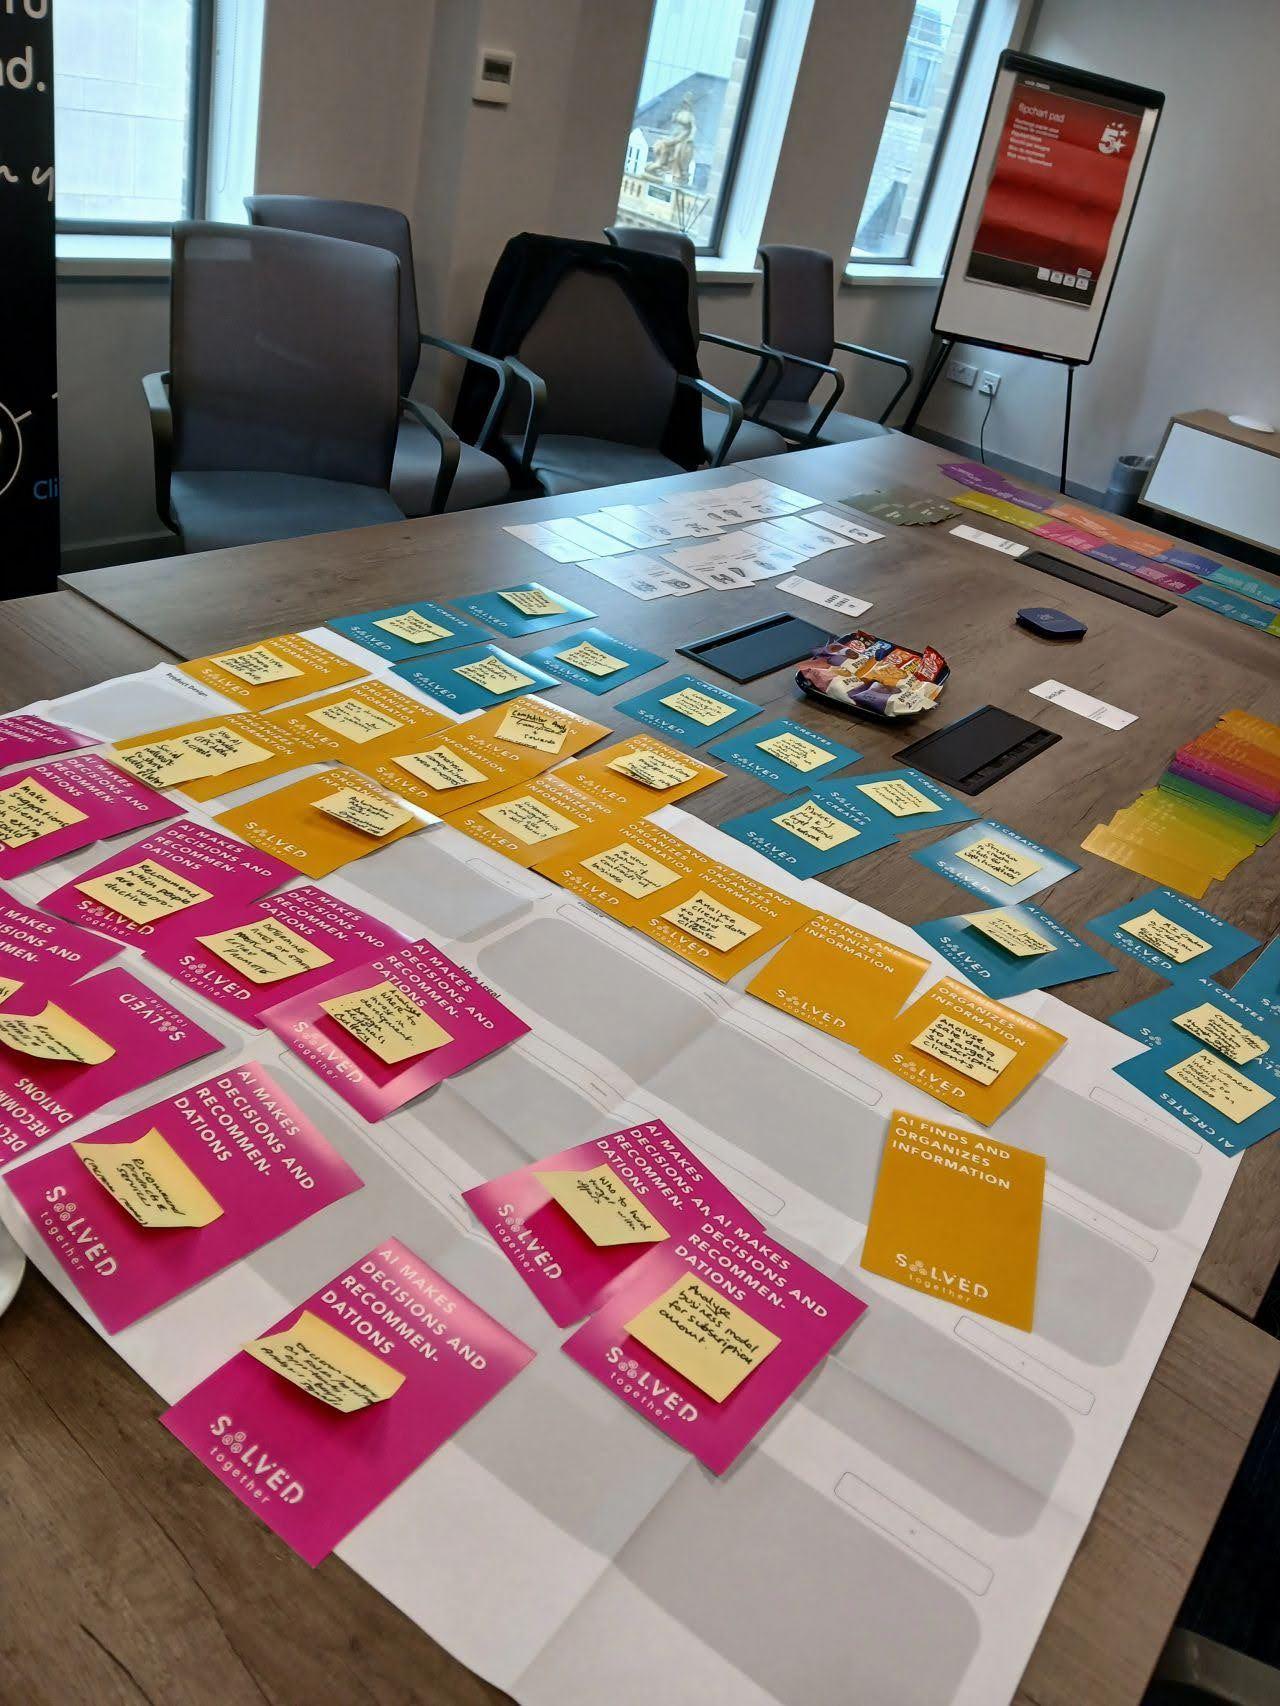
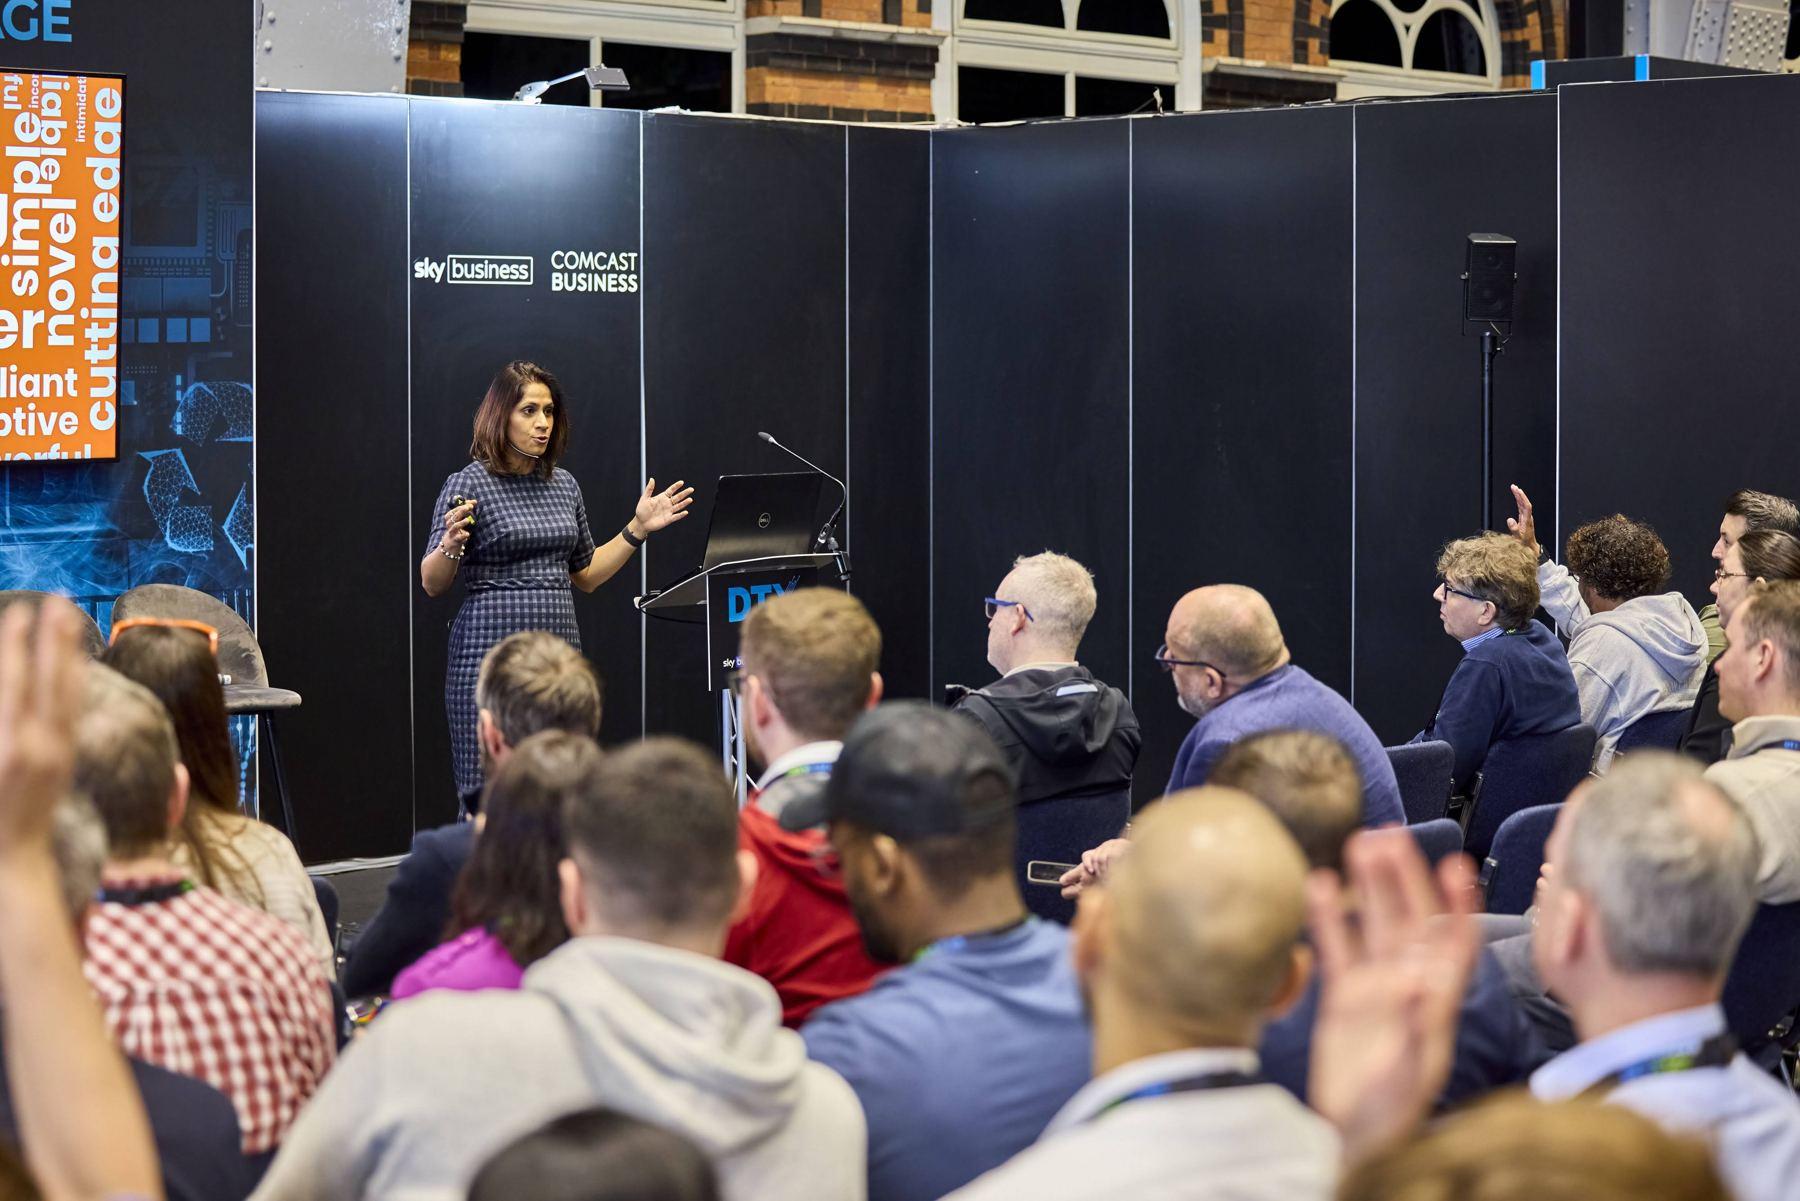
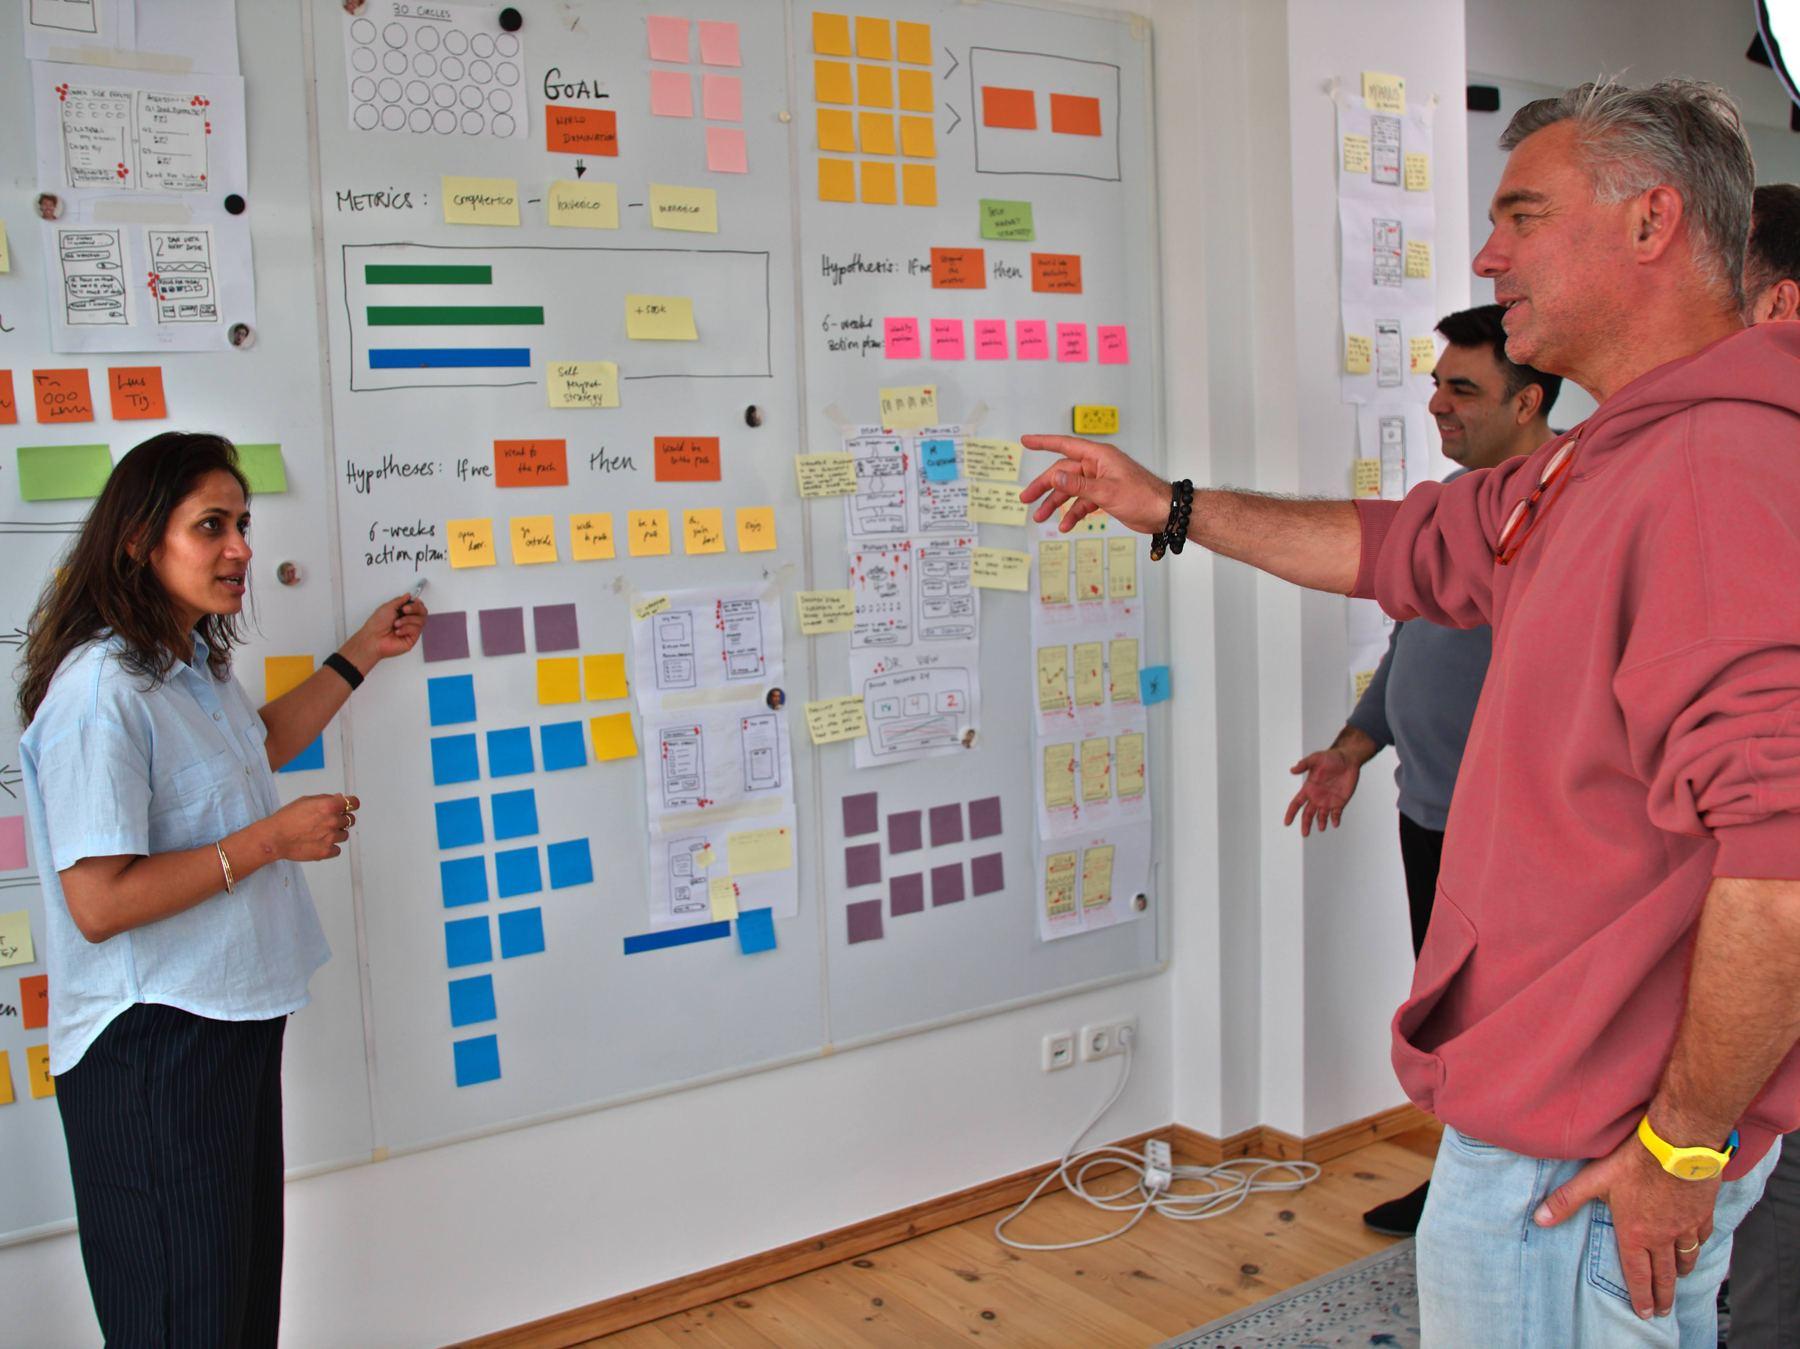
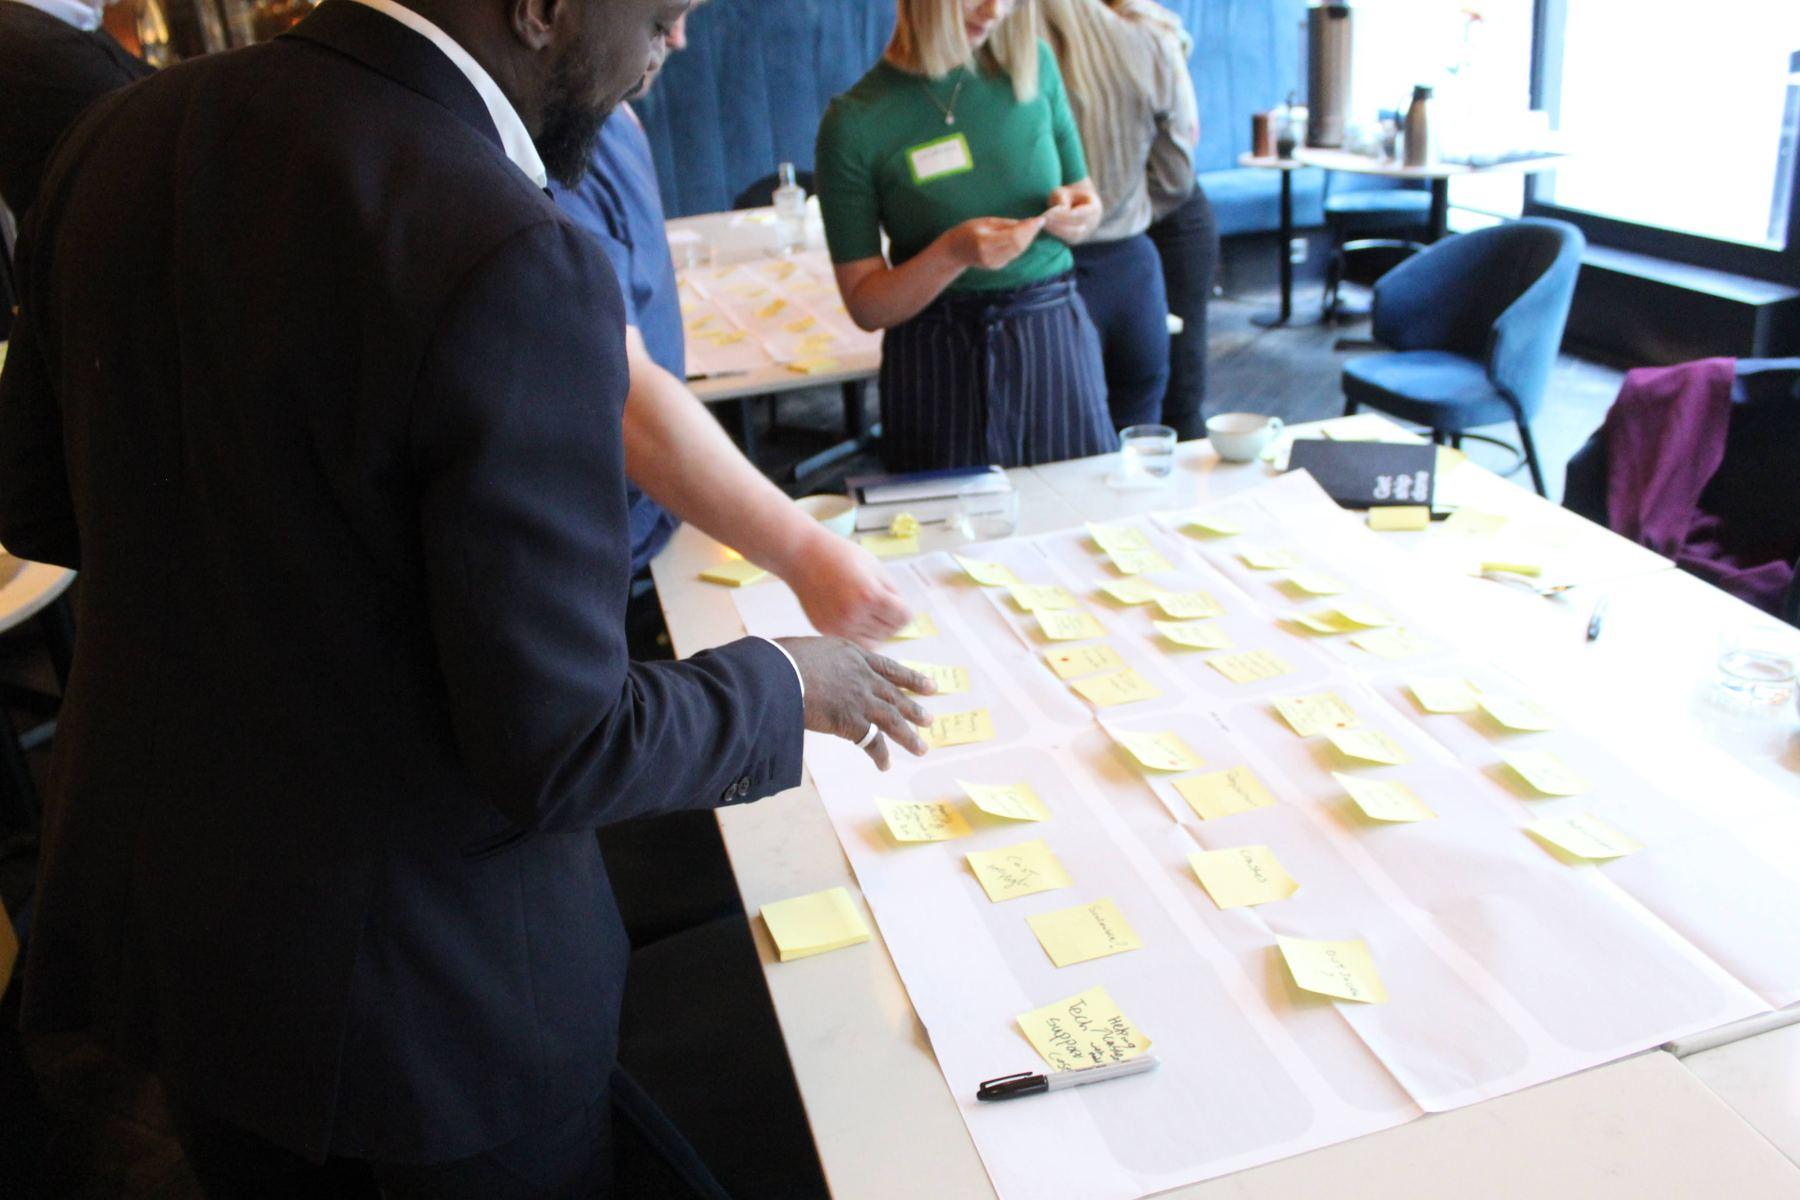
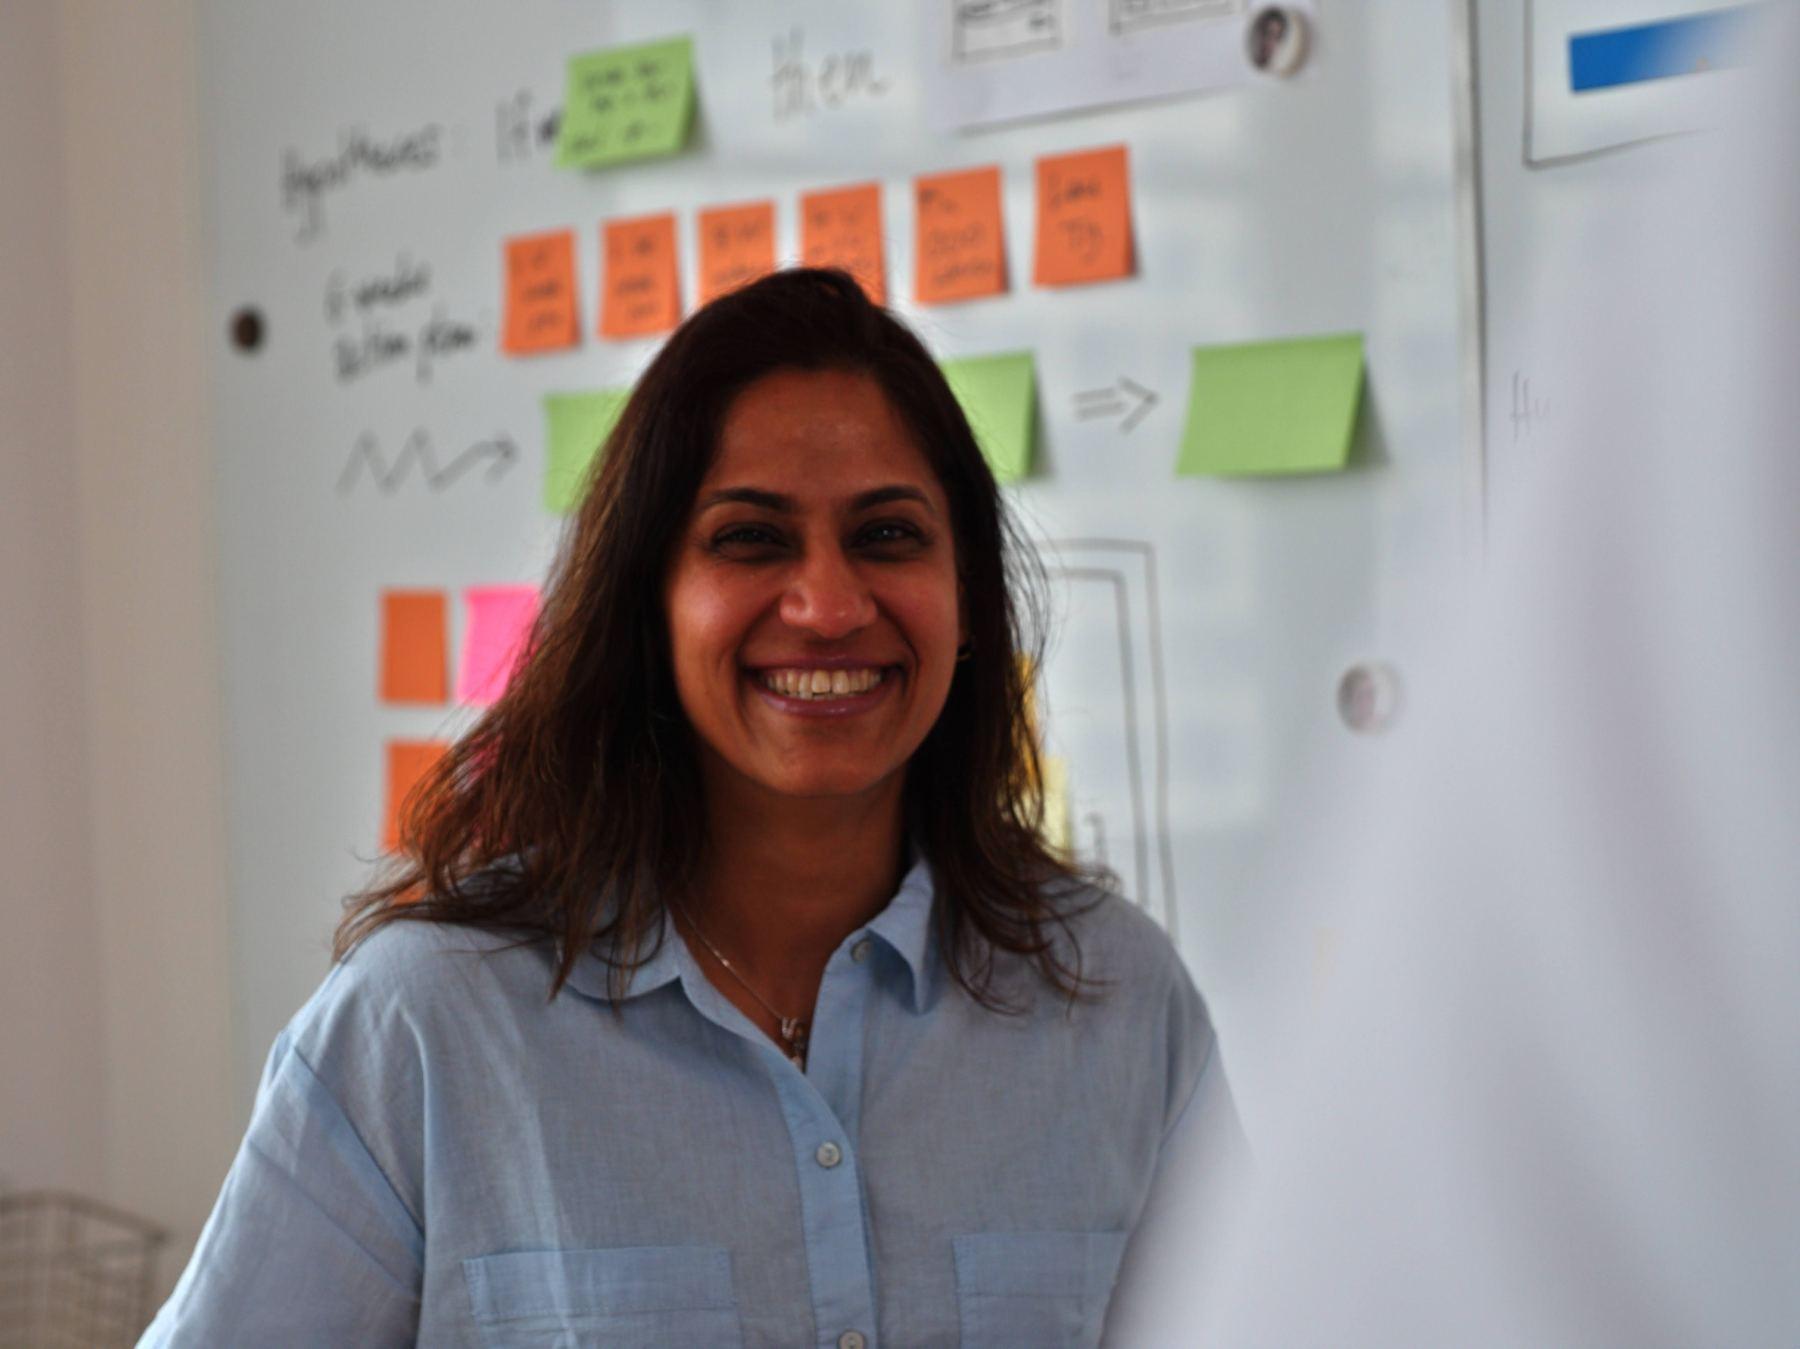
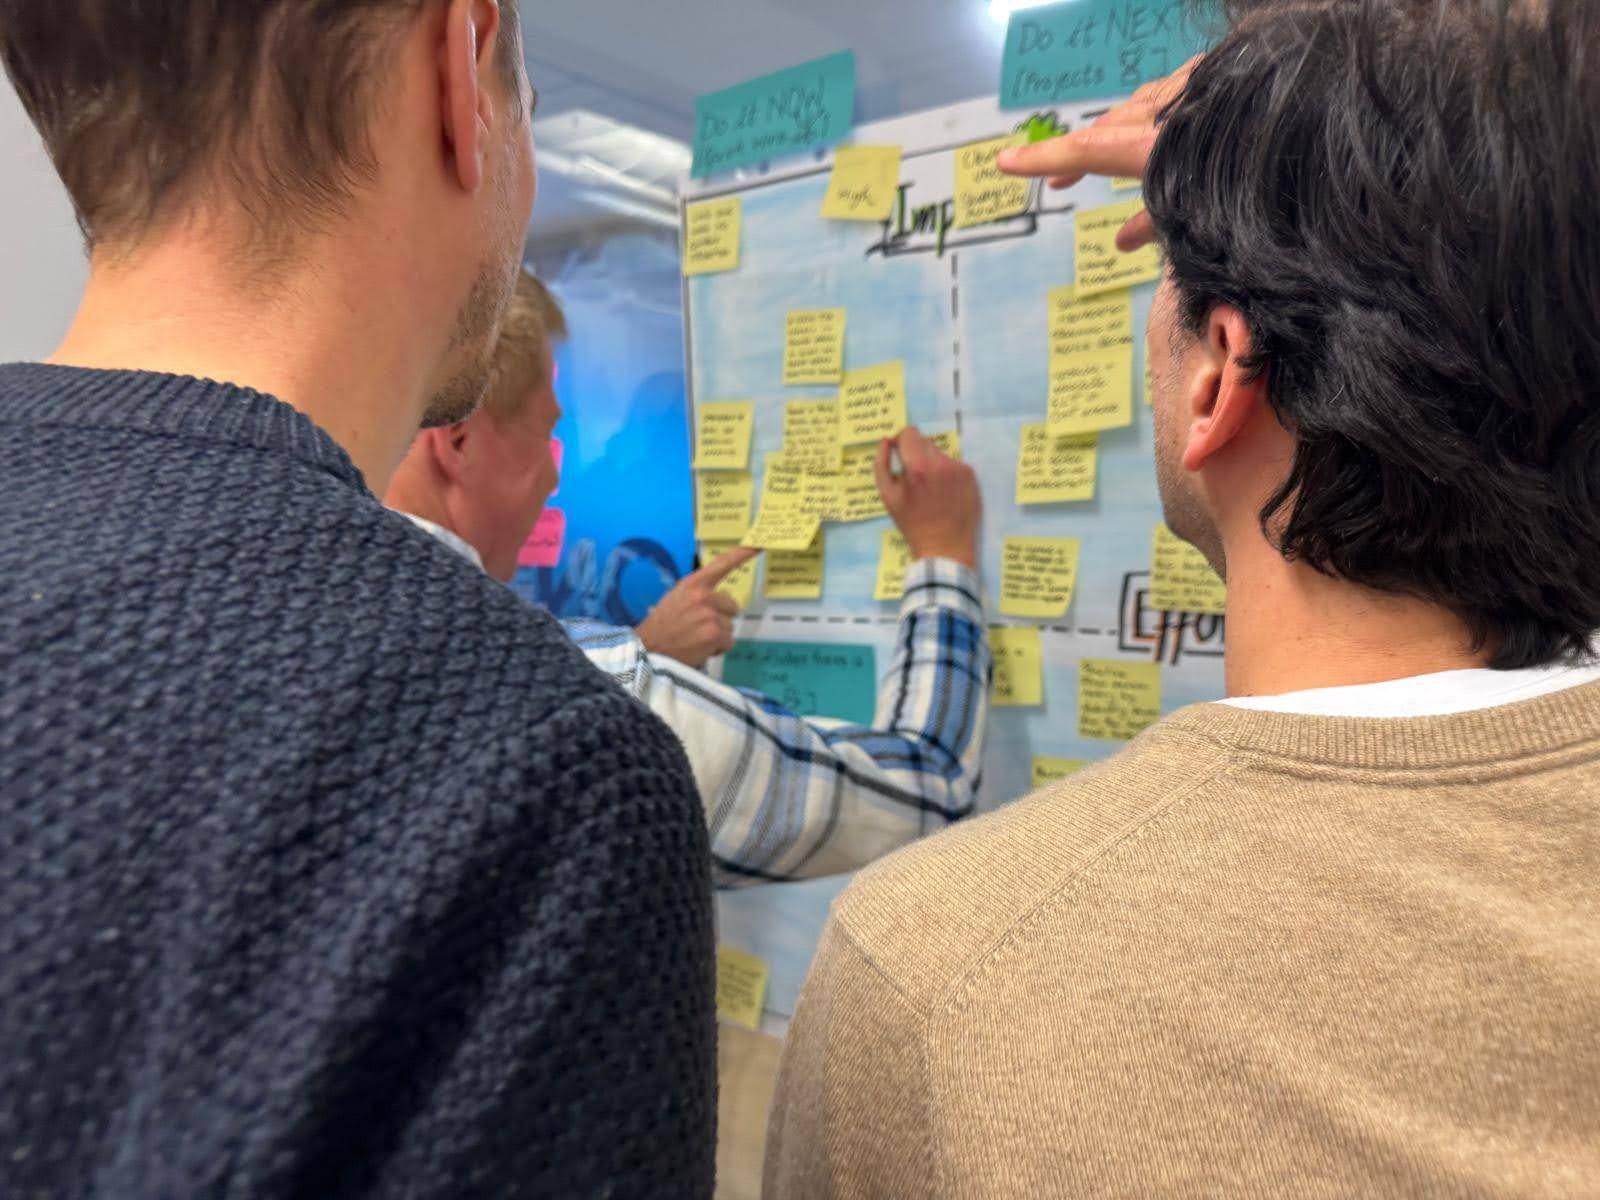
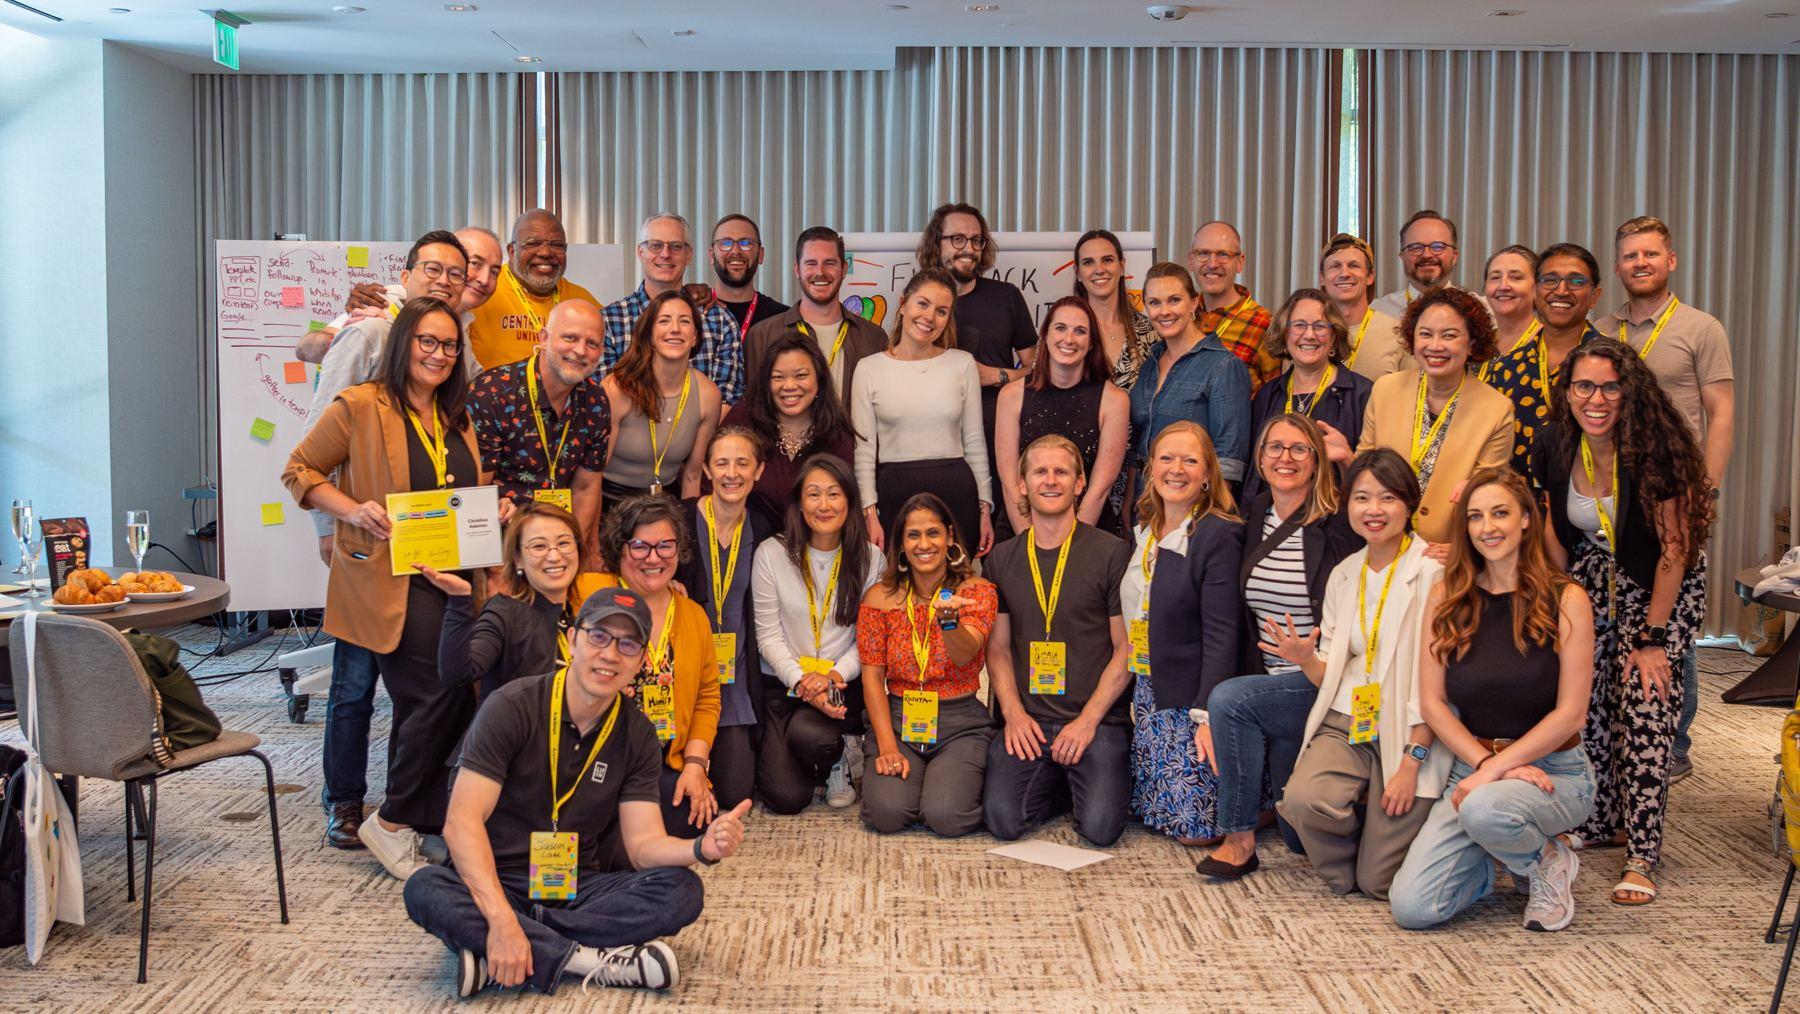
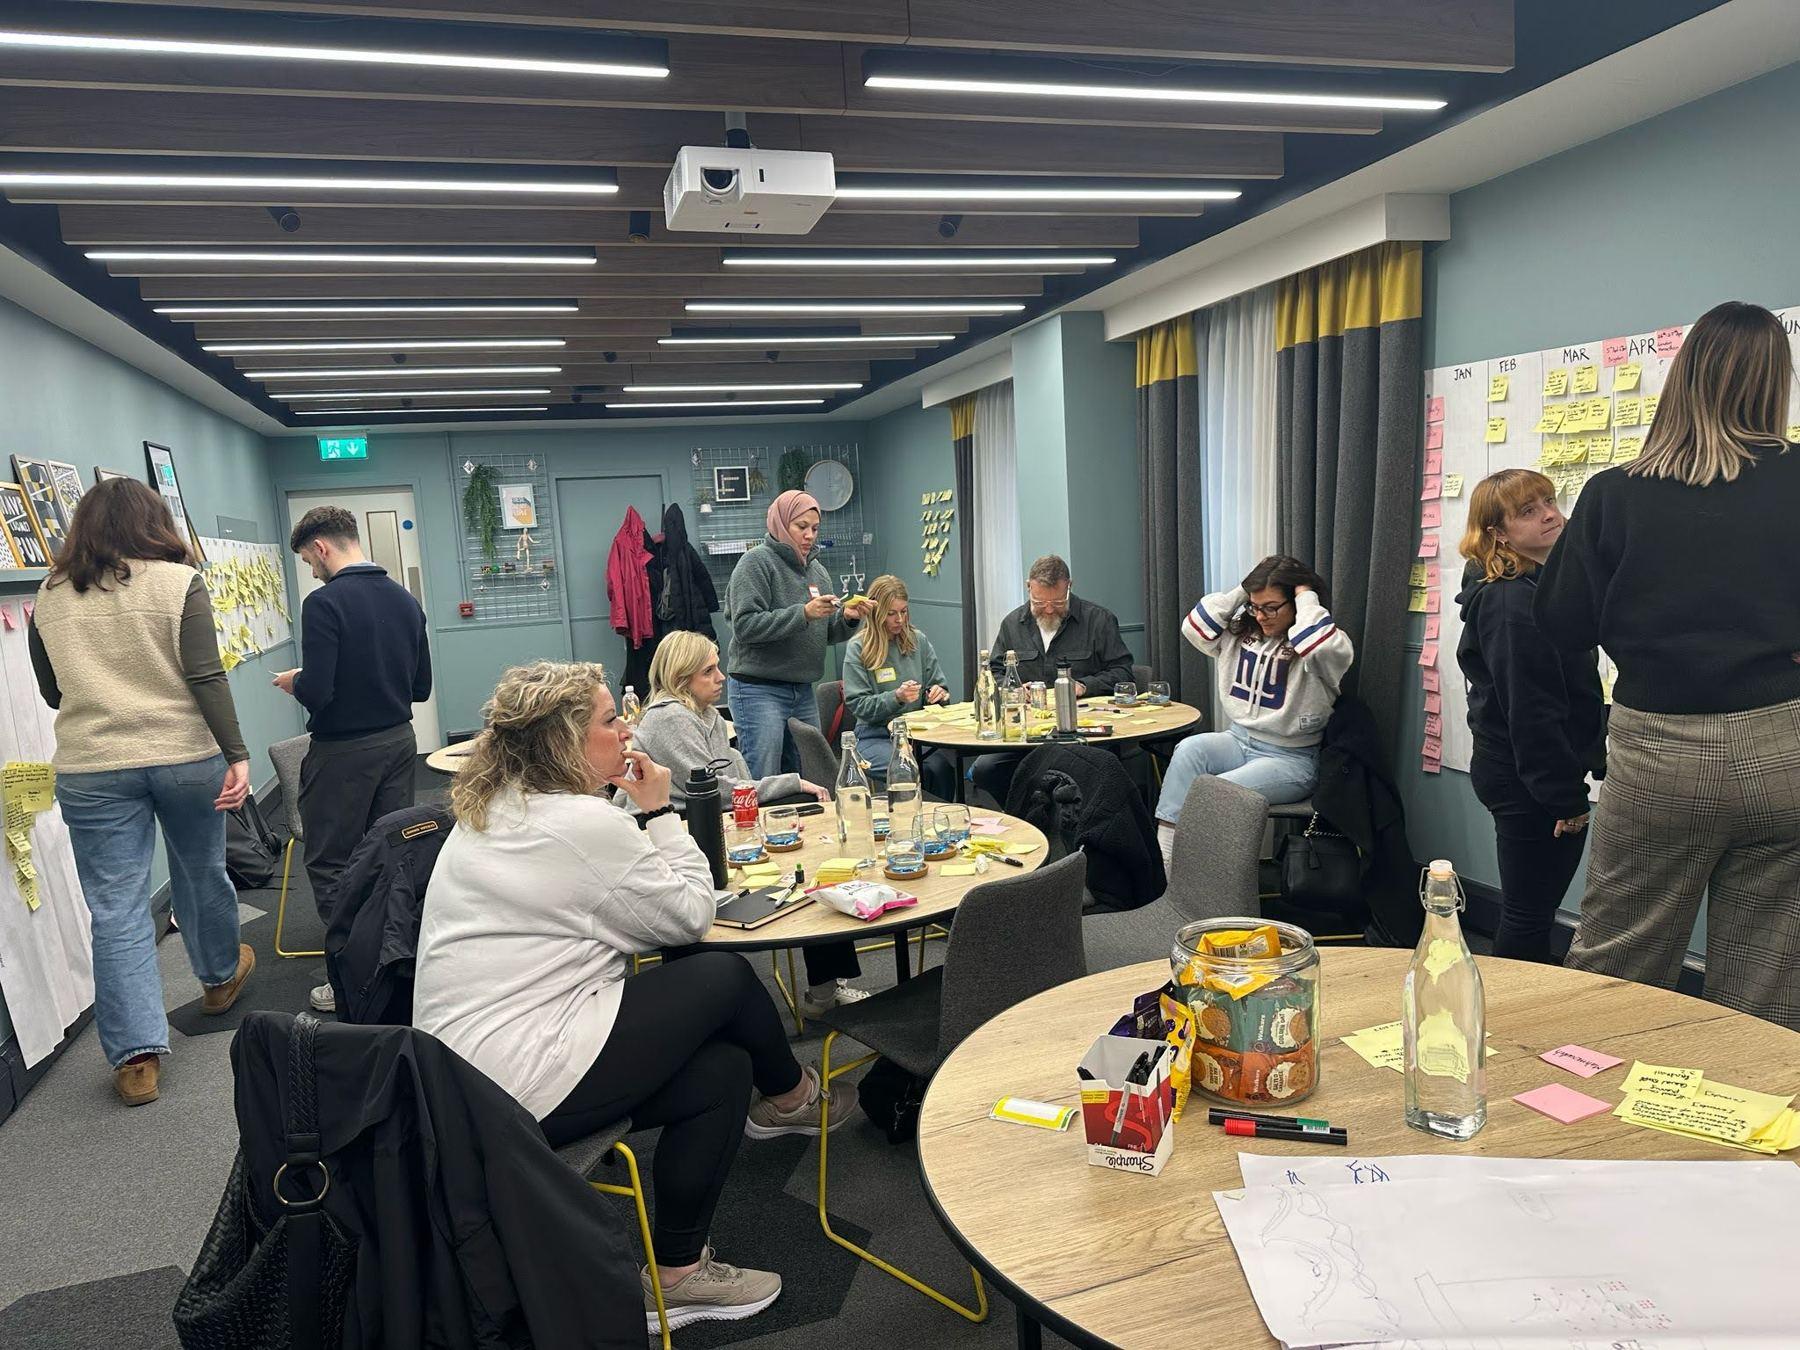
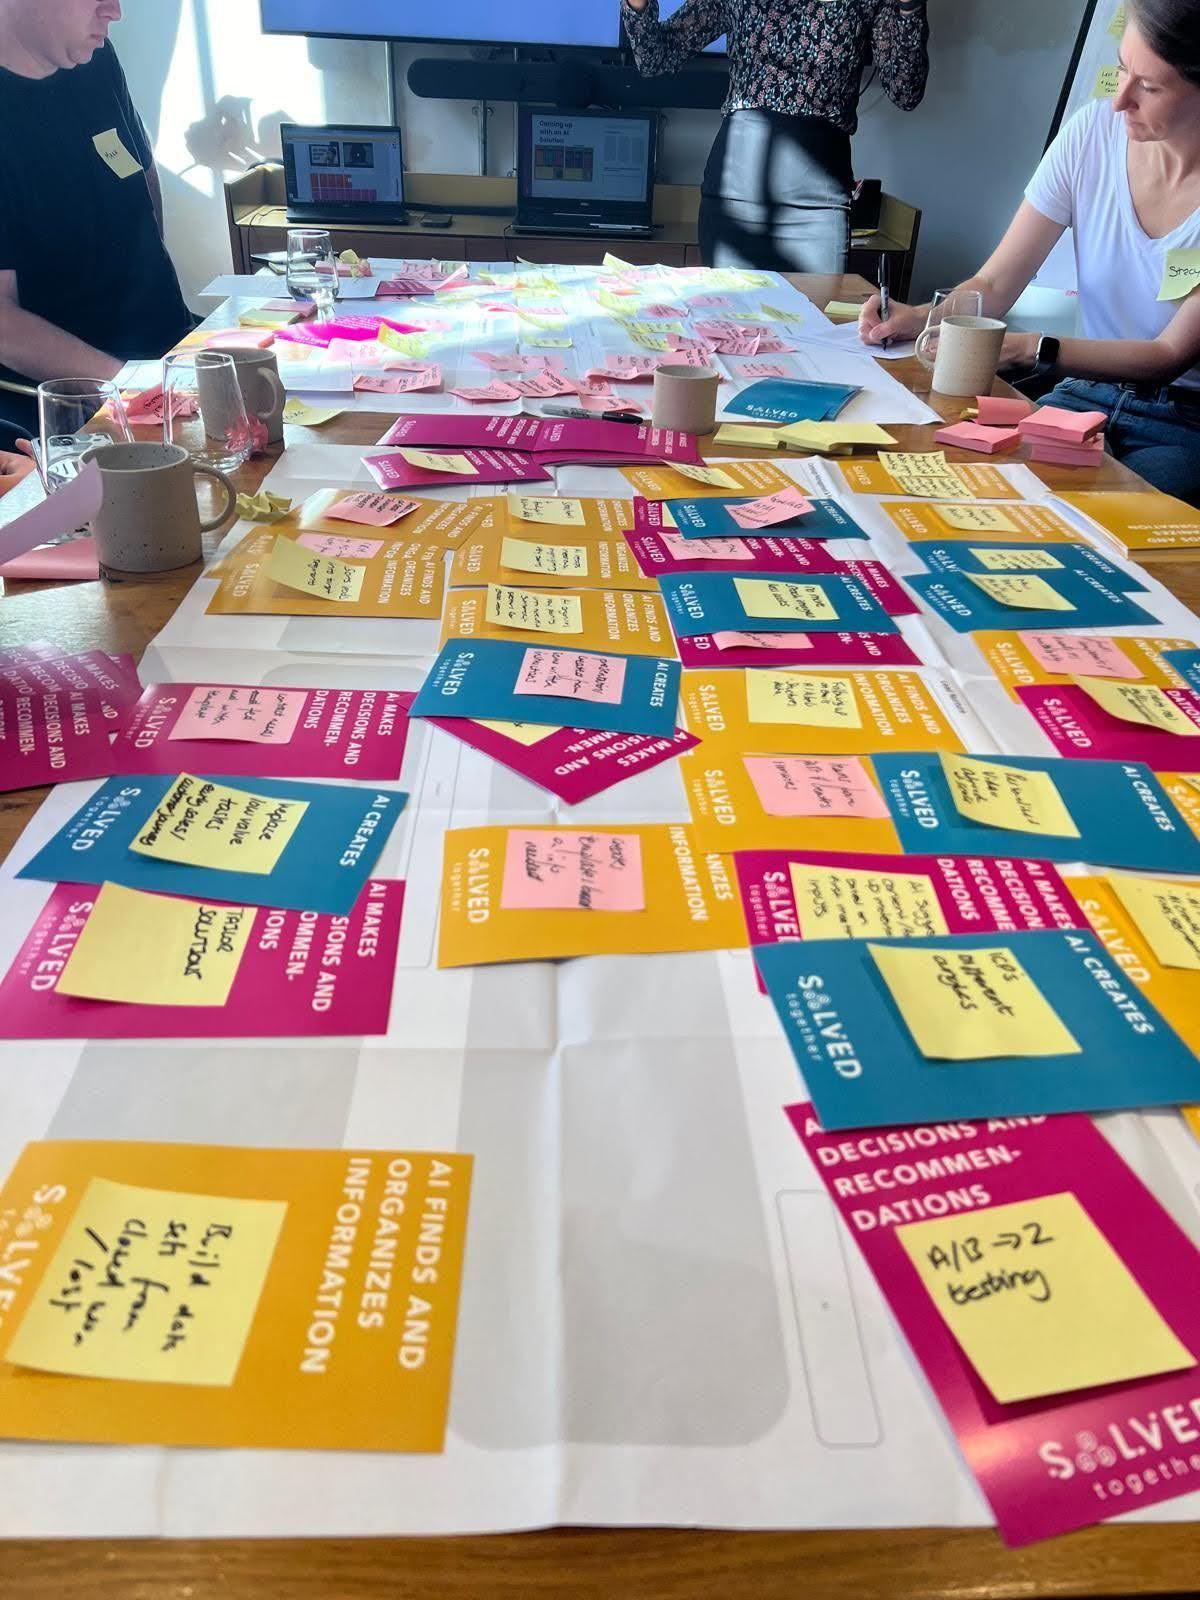
We work in the room, with your people.
The leadership team and the people who do the work design the change together.
04The method
Start from the numbers the business has to hit.
The value creation plan and exit date, or the targets the board has set. Work back to what has to change, and buy the tool last.
- 01
Weeks 1 to 2
Assess
Where you are now. What has been rolled out and what came of it. Structures, tools, systems, data, ways of working and operating model.
- 02
Weeks 2 to 7
Direction
Ask where the business needs to get to, and why it is not there. Clean Sheet the products and services end to end, with cross-functional people in the room together. Case the value, sized, with a roadmap an investment committee can sign.
- 03
Runs alongside
Foundations
Build the skeleton once, so use case two costs a fraction of use case one. Buy or build by size and sector. Stack, data, security, governance and operating model.
- 04
Three-week cycles
Execute
One prioritised value case per cycle, running by the end of it. Processes redesigned, not automated. Change management with the teams whose work changes. Value tracked against the case.
Every month of deciding is a month of margin you do not take.
The method in full05What we are running now
Where the value came from.
3x
sales calls from the same team
No extra headcount
Sales capacity. AI took the admin and the lead generation, so the team spend their hours selling.
£4.4m
saved. A £5m quote, tracking to £600K
Three years to nine months
Legacy ERP replacement. Quoted at £5m over three years. We rebuilt the approach around what the business actually needed.
£5m
a year, case built
Delivery under way
The buying function. Discovery across the buying process, systems and team, then a costed case.
06Behind it
24 years of business transformation. Now focused on AI and the P&L.
Rujuta Singh is an AI Operating Partner and Fractional Chief AI Officer. PwC, Accenture, Wipro and Microsoft before that. Programmes up to £500m, reporting to executive boards.
- AI Operating Partner across a PE portfolio
- AI Lead for a major UK energy enterprise
- AI Advisor for two global investment firms
- 30+ Fortune 500 companies
07Track record
The same problems, solved before AI.
All case studies
08Insights
Short pieces on getting value from AI.
All insightsValue
AI made us faster. The decisions didn't get the memo.
Most AI work is solo. The value sits in the room where decisions get made.
3 min read
Value
AI got cheaper. The bill didn't.
The price per use is falling fast. The spend is rising faster. Price the work, not the token.
3 min read
Governance
Four things your board calls one question.
"Is our AI secure?" is really four questions. Your board will ask the first. Ask yourself the other three.
3 min read
09Get in touch
Start early, so there is time for the results to show.
A paid, 60-minute AI vs. ROI audit (£200) on one business or one portfolio: where AI spend stands, what it has returned, and whether there is value worth going after.
Book AI vs. ROI Audit SessionNot ready to book? Send a note.